Oconee Estate Planning Blog

Serving Oconee County Georgia and the Surrounding Area

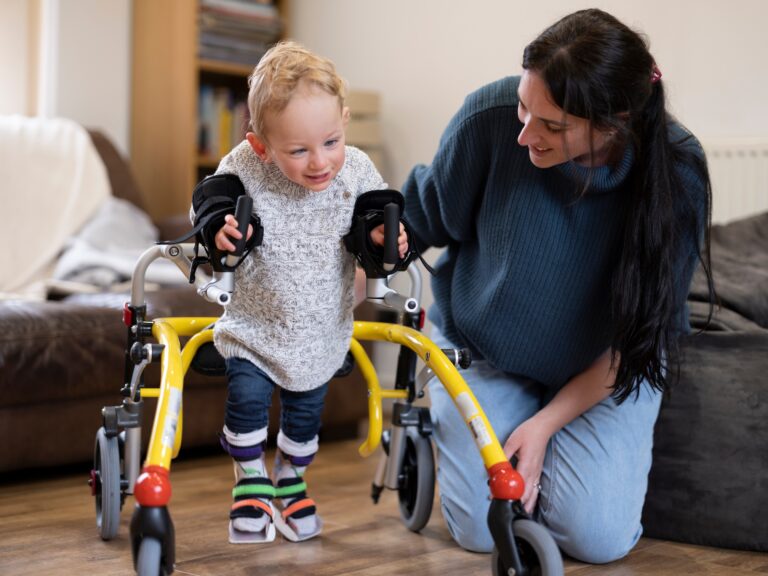
Accessible Housing Basics Guide for People With Disabilities

Takeaways

  • Accessible housing supports safety, dignity, and independence.
  • The right features depend on the person and may change over time, so planning ahead helps preserve options.
  • Accessibility can include mobility features (no-step entry, wider doorways) and sensory or communication supports (visual and haptic alerts, sound reduction).
  • Families can often choose between finding accessible housing and modifying their current home — and sometimes a mix of both.

Accessible housing means having a home you can enter, move around in, and use safely day to day and in an emergency. For many people with disabilities and older adults, accessible housing is essential. It can be the difference between living independently and needing daily assistance for basic activities like bathing, cooking, or getting in and out of the home.

The United States Department of Housing and Urban Development (HUD) reports that 19 percent of American households include someone with accessibility needs, and that almost four in 10 of those households lack key accessibility features such as an entry-level bedroom and bathroom or a ramp. That means many families are trying to make traditional housing work for needs it was never designed to support.

Why Accessible Housing Matters

Accessible features can shape what everyday life looks like — for the person who needs them and for the family members who provide support. Changes in key areas like entryways, kitchens, and bathrooms can affect whether someone can bathe, prepare meals, or leave the house safely without assistance.

Accessible housing is also a quality-of-life issue. When a home is usable, it can support privacy, dignity, and stronger connections to the community.

What “Accessible Housing” Means

Many people may picture a ramp and a wider doorway when they hear “accessible.” Those features can be important, but accessible housing is broader than that.

In everyday terms, accessible housing is housing that can be used safely and comfortably given a person’s body, health, and daily routines. That can include:

  • Physical access (getting in, moving through hallways, using bathrooms and kitchens)
  • Communication access (knowing when a smoke alarm, doorbell, or phone is alerting)
  • Sensory access (lighting, sound levels, clear wayfinding cues)

It can also help to separate three related ideas:

  • Accessible features: Changes that make the home usable now (for example, a no-step entry, installing grab bars, a roll-in shower, or a stair lift)
  • Adaptable housing: A home that is built or chosen with future modifications in mind (for example, enough bathroom space for a wheelchair turning radius even if it is not needed today)
  • Universal design: A design approach that aims to make homes easier to use for as many people as possible, without needing special “add-ons.” Many universal design choices, like lever handles or a no-step entry, can help people across ages and abilities.

Common Home Accessibility Features

No single checklist fits everyone. A home that works well for a wheelchair user may not fully meet the needs of someone with low vision, dementia, or who has hearing impairments.

That said, the following accessibility features often come up because they reduce falls, make daily tasks easier, and allow for safer independence:

  • Stair alternatives: Accessible housing can be ranch-style with no entry steps or can include features such as ramps and elevators to allow people of all abilities access.
  • Parking: Parking may be close to the entrance for better access.
  • Wider doorways and hallways: Wider doorways and hallways, clear floor space, and flat, low thresholds can improve access for wheelchairs and walkers.
  • Bathroom features: Bath and shower grab bars, walk-in or roll-in showers, shower benches, nonslip flooring, and sinks with knee clearance can assist people with mobility challenges.
  • Kitchen features: Easy-reach kitchen appliances, lower counter and cabinet height, pull-out shelves, and open space under sinks or cooktops can help people prepare meals from standing or seated positions.
  • Lighting and visual support: Well-lit areas, additional lighting, and clear pathways can help older adults and people with visual impairments navigate and avoid falls.
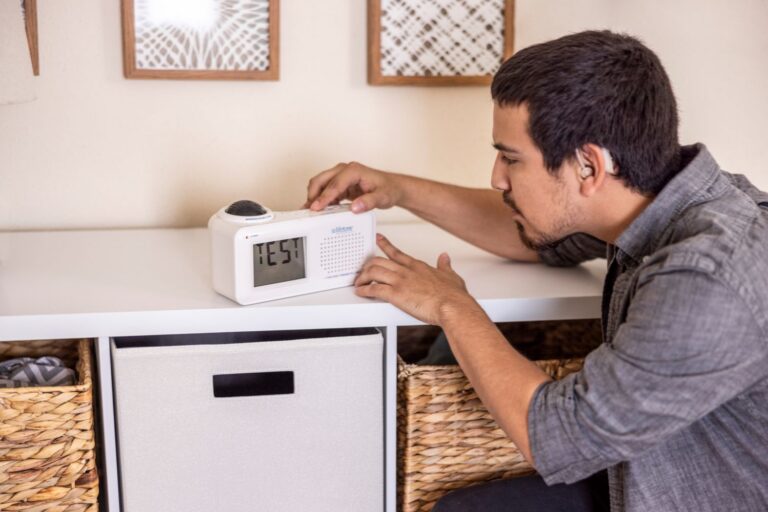
  • Alerts: For people who are Deaf or hard of hearing, accessible carbon monoxide and fire alarms can display visual alerts. Visual or vibrating doorbell and smartphone-connected alert systems can also help people notice urgent signals.
  • Lever door handles: Lever-style door handles are more accessible than traditional knobs as they can be easier for those with arthritis or various mobility impairments to open.
  • Sound and sensory comfort: Sound-dampening materials, soft-close hardware, and designated quiet spaces can support people with sensory sensitivities or who rely on clear sound cues.

If you are thinking about accessibility in rentals or multifamily housing, it can also help to know that some buildings are subject to accessibility design requirements under federal law (separate from the Americans with Disabilities Act). HUD’s overview of the Fair Housing Guidelines is a helpful place to start.

Accessible Housing Options Families Often Consider

Accessible housing is not one “type” of home. Families typically consider a few different paths depending on budget, location, and the person’s preferences.

  • A private home with modifications. This can work well when persons with disabilities want to stay near family, school, work, and health care providers. It can also be a practical option when accessible rentals are limited.
  • An accessible apartment or condo. Some units are built with accessible features or can be modified with landlord permission as a reasonable accommodation.
  • Supportive housing, assisted living, or group home settings. These options can offer built-in supports, which may be appropriate when daily assistance is needed.

How Needs Can Change

Needs can change over time. Families often see housing needs shift because of:

  • A progressive disability or new diagnosis
  • Recovery from surgery or injury
  • Changes in mobility aids (e.g., from a cane to a walker to a wheelchair)
  • Changes in stamina, balance, vision, or hearing
  • A change in living situation (moving out, moving in with family, a caregiver is no longer available)

A practical way to plan is to look for housing that works today while leaving room for tomorrow. For instance:

  • If there are entry stairs, is there space to add a ramp later?
  • If the home has more than one story, is there a realistic plan to one-floor living (or to adding an elevator or chair lift for stairs)?
  • Is there enough bathroom space for a bench, caregiver assistance, or turning radius if needed?

Accessible housing is about fit: a home that matches a person’s needs so daily life can be safer and more independent. If you’re deciding between moving and modifying, it can help to prioritize the features that most directly affect safety and then build from there.

Thinking ahead and anticipating potential challenges can make aging in place and remaining connected to the community more achievable.
Could a Trump Account Cost Your Child SSI Benefits?

Takeaways

  • Trump Account balances are excluded from Supplemental Security Income (SSI) resource calculations while a child is in the account’s growth period but generally become countable beginning January 1 of the calendar year the child turns 18.
  • A balance above SSI’s $2,000 individual resource limit could make a young adult ineligible for SSI and may affect access to Medicaid, depending on state rules.
  • During the calendar year the beneficiary turns 17, the full Trump Account balance may be transferred directly to an ABLE account, which can protect the funds from SSI’s resource limit.

Trump Accounts, a new children’s savings program created by 2025 tax law, began accepting contributions on July 4, 2026. Eligible U.S. citizen children born between January 1, 2025, and December 31, 2028, may receive a one-time $1,000 federal contribution when a parent or other authorized adult enrolls them in the pilot program. Parents, relatives, and others can add more to a child’s account. The idea is to give kids a head start on long-term savings that grows, tax-deferred, until they become adults.

For families of children with disabilities, though, that same growth could create a serious problem. A recent report from the Center on Budget and Policy Priorities (CBPP) warns that Trump Account balances could push young adults with disabilities over the strict asset limit for Supplemental Security Income (SSI), putting their SSI and Medicaid coverage at risk, depending on the state’s rules.

How a $1,000 Deposit Could Create an SSI Problem

SSI provides modest monthly payments to people with limited income and resources who are disabled, blind, or 65 and older. To qualify, an individual generally can’t have more than $2,000 in countable assets, which includes savings accounts, checking accounts, and similar resources. That limit hasn’t been adjusted since 1989.

While a child is under 18, their Trump Account balance won’t count against SSI’s asset limit. Beginning January 1 of the calendar year in which the account holder turns 18, the Trump Account generally becomes a countable resource for SSI purposes. CBPP calculated that even with no additional contributions beyond the initial $1,000 federal deposit, an account growing at just 4 percent per year (well below typical long-term market returns) would exceed the $2,000 limit by the time a child turns 18.

The risk also affects children whose families currently earn or save too much to qualify for SSI. When they turn 18 years old and apply on their own, their Trump Account balance could make them ineligible from the outset.

What’s at Stake Beyond the Monthly SSI Check

Losing SSI eligibility can trigger a chain reaction. In most states, SSI eligibility leads to Medicaid eligibility, although the rules and application processes vary by state. For many people with disabilities, Medicaid pays for essential home- and community-based services, such as personal care aides, therapies, and equipment, that may not be available through other coverage. So, losing SSI can put that Medicaid pathway at risk, not just the monthly SSI cash benefit.

The Narrow Fix: ABLE Accounts

There is a legal way to shelter the savings in a Trump Account: ABLE (Achieving a Better Life Experience) accounts. Created specifically for people with disabilities, ABLE accounts allow up to $100,000 of a beneficiary’s balance to be excluded from the SSI resource limit, and the money can be spent on a wide range of disability-related expenses, such as housing, transportation, education, health care, and more. As of 2026, anyone whose qualifying disability began before age 46 can open one.

The catch, according to CBPP, is timing. The rollover opportunity is available during the calendar year in which the child turns 17. Any funds not transferred during that window generally become countable resources beginning January 1 of the year the beneficiary turns 18. Missing this window could cause the account balance to count toward the SSI resource limit.

What Families Can Do

  • Mark the calendar for age 17. If your child receives SSI or may apply for it as an adult, begin planning the rollover well before the calendar year in which the child turns 17.
  • Open an ABLE account early. You don’t need to wait for the Trump Account rollover to set one up. Starting an ABLE account now and understanding its $100,000 exclusion and rules on eligible expenses makes the eventual transfer easier and gives the family another sheltered place to save.
  • Watch total countable resources, not just the Trump Account. SSI counts many assets added together, such as bank accounts, college savings, and more. A Trump Account isn’t the only thing that can push a young adult over $2,000, so track the full picture.
  • Talk to a benefits planner or disability attorney before the child turns 18. Benefits counselors, including those at Centers for Independent Living and Work Incentives Planning and Assistance (WIPA) programs, can help families coordinate SSI, ABLE accounts, and Trump Accounts.
  • Consider whether SSDI eligibility changes the picture. Social Security Disability Insurance (SSDI), including benefits some young adults can draw based on a parent’s work record, has no asset limit. Families should determine whether a young adult might qualify for SSDI instead of, or alongside, SSI.
  • Ask about a special needs trust for larger sums. If a Trump Account balance or other windfall is expected to exceed what an ABLE account can hold, a properly drafted special needs trust is another established way to hold assets without losing SSI.

Where Things Stand

As of late August 2026, the $2,000 SSI asset limit remains unchanged and no legislative fix specific to the Trump Account conflict has passed. The bipartisan SSI Savings Penalty Elimination Act, which would raise the general SSI resource limits to $10,000 for individuals and $20,000 for couples and index them to inflation, has been introduced in both the House and Senate but has yet to come up for a floor vote.

Advocacy groups are also urging Congress to raise the SSI resource limit and allow Trump Account transfers to ABLE accounts after age 17.

The Social Security Administration has issued guidance explaining how Trump Accounts are treated for SSI purposes. Because implementation details and future guidance may change, families should still monitor SSA updates and confirm how the rules apply to their individual circumstances.

TV Show Explores Senior Housing and Long-Term Care Options

Takeaways

  • Senior Spaces is a new TV show that follows older adults making real housing and care decisions.
  • Most families weigh four paths: aging in place, downsizing, joining a senior living community, or moving to assisted living or nursing care.
  • The best choice depends on health, finances, support network, and what independence means to the senior.
  • Starting the conversation before a crisis helps families make clearer decisions.

Rick and Mary Williams had happily lived in their home in California for 22 years but began to question whether it was the right place for them to grow old.

That question sits at the heart of Senior Spaces, a new television series that follows real older adults as they navigate one of life’s most emotionally charged crossroads: deciding where and how to live the next chapter of their lives.

Hosted by Bryan Devore, a Seniors Real Estate Specialist (SRES), the show airs on the Senior Lifestyle Network, KUSI News in San Diego, and on YouTube. Senior Spaces is not a renovation show, a real estate competition, or a retirement fantasy but an honest look at the intertwined mix of love, loss, practicality, and hope that shapes one of the most significant decisions aging adults and their families will make.

Difficult Decisions

By 2030, all baby boomers will be over 65, making seniors the fastest-growing segment of the American population. Millions of families are asking a question previous generations rarely faced: What happens when staying at home becomes complicated?

The answer differs for everyone. Whether to age in place, downsize, join a 55-plus community, or move into a nursing or assisted living facility depends on health, finances, family proximity, social connection, and personal values around independence.

The decision rarely arrives cleanly. Often, it follows a fall, a diagnosis, the loss of a spouse, or a slow accumulation of moments when managing the house stops feeling manageable. By then, the emotional and practical weight can be overwhelming.

The Four Paths: Understanding Your Options

Aging in Place

For many older adults, remaining in one’s home is not just a preference but a deeply felt need. The home holds memories, identity, and routine. Aging in place can be a rich and workable option but living independently requires honest planning.

Common challenges include:

  • Physical accessibility. Stairs, narrow doorways, and bathrooms not designed for mobility challenges can become serious safety hazards.
  • Isolation. Without social infrastructure, aging at home can lead to loneliness, which research links to cognitive decline and poor health outcomes.
  • Home maintenance. Upkeep can become exhausting or unaffordable.
  • Caregiver burden. Family members stepping in to help may experience significant emotional and physical strain.
  • Emergency response gaps. Living alone without reliable access to help is a real and underappreciated risk.

Resources for aging in place include the AARP HomeFit Guide, the National Aging in Place Council (NAIPC), and Area Agencies on Aging (AAA), which connect seniors with local services including transportation, meal delivery, and in-home care.

Downsizing or Relocating to a New Home

Some seniors choose to downsize to a smaller, more manageable property. This path can unlock home equity, reduce maintenance burdens, and open a new chapter of life in a community that fits better.

Common challenges include:

  • Letting go of decades of belongings, a home where children were raised, and a familiar neighborhood can be emotionally challenging.
  • Simultaneously buying and selling real estate is stressful at any age; navigating the process later in life adds complexity.
  • Adjusting to a new living environment and community and starting over socially in a new place takes energy and time.
  • Getting the market timing right can create financial pressure.

Working with an SRES can make a significant difference. These professionals are trained to understand the unique financial, emotional, and logistical dimensions of senior transitions.

Moving to a Senior Living Community

Active adult communities, 55-plus neighborhoods, independent living communities, and continuing care retirement communities (CCRCs) offer a range of options for seniors who want the independence of their own home or apartment within a community designed for their life stage.

Common challenges include:

  • Cost. Entry fees and monthly charges for CCRCs and independent living communities can be significant and vary widely.
  • Giving up a sense of home. Trading a house full of personal history for an apartment or condo requires psychological adjustment.
  • Navigating the options. The spectrum from active adult communities to independent living to memory care is broad; finding the right fit requires research.
  • Waitlists. High-quality communities often have long waiting lists, making early planning essential.

A Place for Mom and Caring.com are two popular online tools that help families research and compare senior living communities. Many communities also offer trial stays, which can ease the transition and help seniors make informed decisions.

Assisted Living and Nursing Home Care

When daily living activities such as bathing, dressing, managing medications, and eating require consistent support, assisted living and skilled nursing facilities provide round-the-clock structured care. For seniors with dementia or complex medical needs, these settings offer safety and specialized attention that home environments often cannot.

Common challenges include:

  • Cost of care. Assisted living averages $6,200 per month nationally and a semi-private room in a nursing home can exceed $9,000 per month.
  • Quality variation. The quality of care varies from one facility to the next, making thorough research and visits essential.
  • Emotional difficulty. For seniors and families, the transition to a care facility often carries grief, guilt, and a sense of finality that deserves acknowledgment.
  • Advocacy. Family members often must serve as active advocates to ensure their loved one receives attentive, respectful care.

The Long-Term Care Ombudsman Program helps residents of care facilities resolve complaints and understand their rights. Medicare’s Nursing Home Compare tool provides inspection reports, staffing data, and quality ratings for facilities nationwide.

What Senior Spaces Brings to the Conversation

What sets Senior Spaces apart from other housing or lifestyle programming is its commitment to showing the full picture, with its uncertainty, second-guessing, and surprises. In the pilot, Rick and Mary’s story unfolds in ways that challenge assumptions about what seniors want and what ultimately feels right.

The show treats older adults as thoughtful, complex people making consequential decisions, not as a demographic to be managed or a problem to be solved — a meaningful framing in a culture that often sidelines the voices of people in later stages of life.

The show goes beyond square footage and market value. It explores the emotional landscape: the attachments people carry, the family conversations that don’t always go as planned, and the relief that often follows a decision everyone was afraid to make.

Starting the Conversation Early

One consistent insight from senior housing specialists, geriatric care managers, and social workers: families who navigate these transitions best are those who started the conversation before a crisis hit.

That means asking while everyone is still well: What matters most about where you live? What would have to change for you to consider a move? What does a good day look like at 80? These conversations aren’t always comfortable, but they’re far less painful than making the same decisions mid-crisis, without consensus and against a deadline.

Resources such as the National Institute on Aging and ElderCare Locator can help families identify local resources and care managers. Those managers, now often called Aging Life Care Professionals, specialize in comprehensive care planning and navigating complex housing decisions.

The Human Side of a Practical Decision

The question of where to live later in life is not purely logistical. For most people, a home is not just shelter — it is a repository of identity, a symbol of independence, and a place where the self feels continuous across time. Leaving it, even for something better, involves a form of grief.

This dynamic makes Senior Spaces valuable viewing not just for seniors, but for the adult children, spouses, siblings, and friends who stand alongside them during their later-life transitions. Watching someone else move through the process can make it easier to imagine walking the same path yourself.

The show also offers a quiet but important message: there is no shame in needing more support, wanting community, or choosing safety over sentiment. These are not failures of aging but acts of wisdom.

Rick and Mary’s story, like so many others, does not end with a simple answer. It ends with a decision that feels right — not because it was obvious, but because they thought it through together with honesty and care. That is the kind of conversation Senior Spaces is trying to make easier for everyone watching. And in a country where millions of families are wrestling with the same questions, that matters more than most people realize.

Medical Decision-Making for Individuals With Chronic Disease

Takeaways

  • Establishing advance health care directives, health care powers of attorney, and HIPAA authorization forms allows individuals with chronic conditions to control their medical decisions and information, even if they become unable to communicate.
  • These documents provide peace of mind for patients and their families by offering clarity, reducing stress, and ensuring medical care aligns with personal values.

Living with a chronic health condition often means navigating a complex health care system, managing ongoing treatments, and making difficult medical decisions. For many, the uncertainty of how their health may progress raises important questions: What will happen if I can’t make my own health care choices? Who will speak for me if I become unable to express my wishes?

The answers lie in legal documents such as advance health care directives, health care powers of attorney, and HIPAA authorizations. These tools allow people to maintain control over their care and ensure their voices are heard, even if they cannot advocate for themselves.

Why These Documents Matter

Chronic health conditions such as kidney disease, diabetes, or cancer can sometimes lead to sudden complications or long-term changes in decision-making ability. Planning ahead reduces stress for patients and families by providing clarity and direction in critical moments.

Without formal documentation stating a patient’s wishes, medical professionals are generally obligated to provide life-sustaining treatment in emergencies. Family members may face a similar struggle with making difficult choices, sometimes leading to disagreements or legal disputes.

Advance health care planning empowers individuals to take charge of their health care journey and removes the guesswork for loved ones and medical professionals.

Advance Directive

An advance health care directive, sometimes called a living will, is a written document that outlines your preferences for medical care if you become unable to communicate. It can address issues such as:

  • Life-sustaining treatment preferences. Do you want to be placed on a ventilator if you stop breathing?
  • Artificial nutrition and hydration. Would you want to use feeding tubes or IV fluids if you become unable to eat or drink?
  • Resuscitation orders. Do you want CPR performed if your heart stops?
  • Pain management. Should comfort and quality of life take priority over aggressive treatment?

Advance directive forms can be as detailed or as broad as you want. You can also update them as your health condition or beliefs change.

Health Care Power of Attorney

A health care power of attorney (POA), sometimes called a medical POA or health care proxy, designates a trusted person, often a spouse, family member, or close friend, to make medical decisions on your behalf if you become unable to make decisions or cannot express your wishes.

The chosen representative, known as a health care agent or proxy, can speak with doctors and other providers about treatment options. They can also access medical records to make informed decisions. An agent can consent to or refuse medical treatments based on your expressed wishes and advocate for your preferences in hospitals or other care settings.

Unlike an advance directive, which provides specific instructions, a medical POA allows flexibility. This is especially helpful when situations arise that aren’t clearly outlined in an advance directive.

HIPAA Authorization Form

Advance directives and health care powers of attorney focus on decision-making. The Health Insurance Portability and Accountability Act (HIPAA) form focuses on protecting your medical information.

Without written authorization, health care providers may be unable to share details about diagnoses, treatments, or test results, even with close family members. A HIPAA authorization form allows you to designate specific people, such as a health care proxy, spouse, or children, who can access your medical records.

Having a HIPAA authorization form ensures that the people you trust have the information they need to make informed health care decisions on your behalf.

Putting These Documents in Action

Ensure that your health care documents reflect your wishes and will function as you intend by:

  • Reflecting on your values. Consider what quality of life means to you and what treatment decisions you would or wouldn’t make.
  • Talking with your loved ones. Explain your preferences with family so they understand your choices.
  • Choosing your health care proxy carefully. Pick someone who understands your values, can handle stress, and will advocate firmly on your behalf.
  • Completing all applicable health care forms. Each state has its own legal guidelines for advance directives, POAs, and HIPAA forms.
  • Reviewing your health care documents with professionals. Discuss your documents with your doctor and an attorney to ensure they are clear and valid.
  • Sharing copies of your signed documents. Give signed copies of these documents to your proxy (agent), family members, and doctors. If possible, upload them into your electronic medical record.
  • Reviewing and updating these documents regularly. Revisit your documents every few years or after major health changes.

Peace of Mind Through Planning

For individuals living with chronic illnesses, uncertainty about the future can be daunting. Taking proactive steps to document health care wishes can provide reassurance that your values will guide your medical care, even if you cannot speak for yourself.

By planning ahead, you not only protect your autonomy but also provide your loved ones with a clear path forward, thus reducing stress, preventing conflict, and ensuring that your medical care reflects what matters most to you.

Choosing Assisted Living Memory Care for Dementia

Takeaways

  • Assisted living can be a good fit for someone with dementia who needs help with daily activities and supervision but does not require 24/7 medical care in a nursing home.
  • Memory care usually means a more structured, dementia-informed environment within assisted living, but services and staffing standards vary by state and by facility.
  • The quality and dementia-specific supports can vary widely — so families should ask detailed questions.
  • Look beyond amenities: staffing, dementia training, safety practices, and medication support often matter more than the building itself.
  • Expect costs to rise as needs increase. Ask what is included, what triggers price changes, and what happens if funds run low.
  • Before signing, have a licensed attorney review the contract for fees, discharge and transfer rules, dispute-resolution clauses, and what happens if care needs change.

Assisted living is playing a growing role in dementia care. According to a recent report from AARP, more people 85 and older now reside in assisted living than in nursing homes. Of assisted living residents, 44 percent live with Alzheimer’s disease or another dementia, and many communities are responding by adding or expanding memory care units.

For families navigating this landscape, the expansion of memory care is both an opportunity and a challenge. On one hand, assisted living can feel less institutional than a nursing home and may support quality of life for older adults who are still physically capable. On the other hand, assisted living and memory care are regulated mostly at the state level, and the name on the brochure doesn’t always tell you what level of care a facility can truly provide.

What Is Assisted Living?

Today, 1 million Americans live in assisted living communities. Assisted living is often described as a middle ground between independent living and a nursing home. It typically combines:

  • Housing (a private or semi-private apartment or room)
  • Meals and housekeeping
  • Supervision and help with activities of daily living (ADLs), like bathing, dressing, and eating
  • Some health-related services, which may include help with medication administration

Assisted living is not the same as a nursing home, which provides a higher level of medical oversight and skilled nursing care. Also, note that services offered by assisted living facility may vary by facility and by state.

If your loved one needs round-the-clock medical care, you may need to look beyond assisted living.

How Do Assisted Living Facilities Serve Residents With Dementia?

Assisted living facilities primarily serve people with dementia by offering help with ADLs, which can become increasingly challenging as people age and dementia progresses. Some assisted living facilities provide dementia training to staff, but it is more common in specialized memory care facilities.

Not all assisted living is memory care, but many facilities offer it as a distinct, more specialized option within the same community.

Memory care facilities specifically serve people with dementia. Many states have developed a special licensure for assisted living facilities marketed as “memory care.” In those states, memory care facilities generally, but not always, have greater oversight of resident safety and staff receive dementia training.

What Role Do Family Caregivers Play?

While assisted living offers some support for people with dementia, family caregivers typically continue to provide support. Assisted living facilities typically offer limited hours a day of personal care services. When a resident’s needs exceed this, family caregivers often step in.

This caregiving can involve out-of-pocket costs. Family caregivers of assisted living residents with dementia report spending just shy of $9,000 annually on caregiving related costs, including things like personal supplies, transportation, and gaps in facility coverage.

What Questions Should Families Ask a Facility Before a Loved One Moves In?

Before a loved one with dementia moves into an assisted living facility, families should consider what services the facility provides and whether it can meet the needs of their loved one. As dementia progresses, the resident’s needs may increase over time, and a good facility should be able to adapt to changes in those needs.

Cost is also a major consideration. In 2024, the median annual cost of assisted living was $70,800, while the median income for adults 75 and older was $47,790. Facilities may charge additional fees for certain services, which can add up.

Keep in mind that Medicare does not pay for long-term custodial care, so most assisted living residents pay out of pocket. If funds run low, families often look to Medicaid. However, Medicaid rules vary by state, and Medicaid generally does not pay for assisted living room and board (although some states may cover certain care services for eligible residents).

The following questions can help families consider whether an assisted living facility is a good fit for a loved one with dementia.

  1. How many hours a day of help with daily tasks are provided?
  2. Who provides hands-on care and who administers medication?
  3. Are staff members trained in dementia care? How many residents does each staff member typically care for?
  4. Is there a nurse on site? If so, when?
  5. Is this a memory care facility?
  6. Is the memory care area secured? What happens if a resident is wandering and tries to leave?
  7. What supports are provided for residents with dementia?
  8. As dementia progresses, how does care adapt to meet a resident’s needs? How often is the care plan reassessed?
  9. What are the monthly and yearly fees? Are services such as help with medication billed à la carte?
  10. How do you respond to agitation, refusal of care, or sundowning?

What Should Families Understand in a Contract Before Signing?

A contract is more than a financial document. It governs key rights and expectations.

Because assisted living is largely regulated at the state level and residents’ rights can depend on state rules and contract terms, have a licensed attorney review the facility’s contract before you sign it.

Elder law attorneys can help families understand:

  • the costs of services listed in the contract,
  • when fees can increase and how increases are communicated,
  • what happens if the resident needs to move out of the facility, and
  • how disputes are handled.

Finding the right fit takes time, but asking the right questions about care, costs, and contracts is how families advocate for their loved one and find a place where they can truly thrive.

Federal Government Helps with COVID-Related Funeral Costs

The Federal Emergency Management Agency (FEMA) — the government agency handling the burial cost program — released its policy for the program, reports AARP’s recent article entitled “FEMA to Help Cover Funeral Costs for COVID Victims.”

“The COVID-19 pandemic has caused immense grief for so many people,” Acting FEMA Administrator Bob Fenton said in a statement. “Although we cannot change what has happened, we affirm our commitment to help with funeral and burial expenses that many families did not anticipate.”

Note that FEMA has already had reports of scammers reaching out individuals claiming to offer help applying for this funeral assistance. If anyone contacts you about this program before you have personally registered for aid, it’s a scam. FEMA says it won’t reach out to people prior to registration.

The maximum amount of financial aid available is $9,000 per funeral. This assistance can be used to help with expenses for funeral services and interment or cremation. FEMA has said that a death must meet at least these criteria to qualify for aid:

  • The death certificate must state that the death was caused by COVID-19
  • The death happened in the U.S.; and
  • The person applying for funeral assistance must be either a U.S. citizen, a non-citizen national, or a qualified alien, who incurred the funeral expenses after January 20, 2020.

FEMA is taking calls for assistance applying for funeral aid at 844-684-6333 between the hours of 8am and 8pm Central time, Monday through Friday.

FEMA says if you had any COVID-19 funeral expenses last year, you should make sure to collect all the documentation for all of your costs. This includes:

  • An official death certificate that links the death directly or indirectly to COVID-19 and shows the death occurred in the U.S.
  • Funeral expense documents, like receipts or a funeral home contract that include your name, the deceased person’s name, the amount of the funeral expenses and the dates those expenses were incurred; and
  • Proof of funds received from other sources that went specifically toward the cost of the funeral.

This assistance program won’t be able to give you money for costs that were paid for by burial or funeral insurance or with financial aid received from voluntary agencies, government agencies, or other sources.

If you qualify for funeral assistance, you can receive a payment by mail or through direct deposit when you apply for aid.

Reference: AARP (April 7, 2021) “FEMA to Help Cover Funeral Costs for COVID Victims”

Suggested Key Terms: Elder Law Attorney, Elder Care, Funeral Arrangements, Burial, COVID-19 (coronavirus)

What Is Science Doing About Hearing Loss?

Thanks to advances in technology and medicine like artificial intelligence and gene therapy, hearing research is producing significant innovations. AARP’s recent article entitled “Three Game-Changing Innovations for Those With Hearing Loss” looks at a couple of them, in various stages of development.

  1. Eyeglasses That Turn Speech into Subtitles. With these, you’ll be able to read what people are saying. An app on your smartphone would listen to a conversation and transcribe the speech into sentences in real time. The text would be sent instantaneously to your enhanced eyeglasses, which would create subtitles. Vuzix, a tech company, recently released smart glasses that work with transcription software. Automatic speech-to-text programs have proliferated in recent years, and live computer-generated captions are now available on most videoconferencing platforms. Smartphone apps can also generate real-time transcriptions for in-person conversations. However, the issue is that users have to be in front of a PC or looking at a phone, which detracts from full social engagement. However, companies are making subtitles more natural, by using “smart glasses” technology, which can project text to a user’s field of vision in a comfortable, nonintrusive way. We may see this in a few years.
  2. An App That Lets You Hear Someone in a Crowded Room. This technology can isolate a person’s speech in a noisy environment, which would solve what scientists call the “cocktail party problem.” An app would “listen” to the soundscape surrounding you and separate out different streams of sound, including voices, ambient music and other background noise. It would then isolate the sound you want to hear based on the direction you’re facing — and reduce everything else. The cleaned-up sound would then be delivered straight to your ear through your hearing aid, cochlear implant, or earbuds. Powerful de-noising programs look to be available on hearing technology within five years.
  3. Drug Therapy That Regrows Cells That Help Your Hearing. Your body would repair damage to your inner ear — like when a salamander regrows his tail. A drug delivered into your inner ear would turn on chemical switches to regrow the cells responsible for hearing and most hearing loss. Those born with hearing loss or those who lose hearing later in life would get injections to restore some or all of their hearing. This hair cell regeneration would be ideal for anyone who’s lost hearing because of missing or damaged hair cells. However, this isn’t anticipated to be available very soon. Some hair cell regrowth therapies using different methods are currently in human clinical trials. There are trials being conducted at Novartis, Eli Lilly, Frequency Therapeutics, and Pipeline Therapeutics. However, most of this work is still being tested in the lab.

Reference: AARP (August 2, 2021) “Three Game-Changing Innovations for Those With Hearing Loss”

Suggested Key Terms: Senior Health

Who Inherited from the Painter Bob Ross?

Like many painters before him, Bob Ross’s image only took hold after his untimely death. He’s now a pop culture icon, and is featured as bobbleheads, Chia pets and has his own cereal.

However, there’s a reason why we see so much more of the gentle painter than ever before. That’s because of a legal battle for ownership of Ross’s name. That was the only item of value in his estate, which is rare for celebrities of his caliber.

Wealth Advisor’s recent article entitled “Here’s Who Inherited Bob Ross’ Estate, And Where They Are Now” reports about what happened to his estate, who controls it and where they are today.

The Daily Beast wrote that Ross is “a smash hit on social media, where he feels more like a Gen-Z influencer than a once semi-obscure PBS celebrity who rose to fame in the 1980s on the back of his bouffant hairdo, hypnotic singsong baritone and a timeless message about the beauty of the world around us.”

However, he wouldn’t have become a household name, if not for Bob Ross Inc. The battle began when the artist met Bill Alexander, a celebrity painter who had a show on PBS, in 1978. Alexander gave him a job as a traveling art instructor. Ross met Annette and Walt Kowalski at a class, who recently lost their son, and who wanted to learn how to paint.

The Kowalskis convinced him to come to Washington, D.C. to teach. They eventually made a deal: they’d give him a stipend and room and board, if he’d teach more classes that they’d arrange in the area. PBS then asked Ross to do a show like Alexander’s, and Dennis Kapp, the owner and CEO of the art-supply company Martin F. Weber, wanted to develop a line of supplies with him too. Soon, The Joy of Painting was born. However, to look after the supply company with Kapp, Ross and his wife Jane, and Annette and Walt signed documents to create Bob Ross Inc., with all four of them being equal partners.

At the end of the 1980s, all four partners were making $85,000, and in the early ’90s, Ross made around $120,000. However, he wanted to branch out, and when he did, the happy days were at an end. When Ross’s health started to decline, Walt “declared war” and sent Ross documents saying the Kowalskis owned everything, but they’d agreed that Ross and his heirs would get 1% of the revenues for the next decade. Ross never signed anything, and in fact, he quickly changed his last will to make it harder for the Kowalskis to steal his name and likeness.

Those changes to his last will included “a clause specifically addressing his name, likeness and the rest of his intellectual property. All of those rights were to go to Steve and one of Bob’s half-brothers.” His third wife replaced Annette as the administrator of his estate. In July 1995, the painter lost his battle to cancer.

When Ross died, Bob Ross Inc. was totally owned by the Kowalskis. However, they wanted it all, including his name and likeness. Then what one of Ross’s good friends calls “Grand Theft Bob” began.

Steve did not know about the final amendment until 20 years later when his uncle Jimmie, the estate’s executor, informed him. When Ross died, he was worth $1.3 million. Half of that was his third part of Bob Ross Inc., and there was also cash, stocks and property to divide.

The Kowalskis went after Ross’s art supplies and artwork and made “claims against the estate for business and personal reimbursements,” charging Ross’s widow with hefty lawsuits and suing PBS and the children’s show Ross guest-starred on. In 1997, Jimmie, Ross’s brother, settled the lawsuit, practically handing over everything to the Kowalskis. In 2012, their daughter Joan took over, opening up the realm of merchandising for the company.

However, there was still a “grey zone” in how Bob Ross Inc. could truly own Ross’s name and likeness. After learning about that amendment in Ross’s will, Steve went after Bob Ross Inc. but didn’t win his case against Bob Ross Inc.

Joan did strike a deal with him: if he surrendered his rights to Ross’s name and likeness, he could print his name on anything he wanted.

The good news was that Steve was able to return as an art instructor, and thanks to Bob Ross Inc., Ross was bigger than ever. That helped class sizes, and students came in masses to learn the iconic style. Steve gets to run his father’s estate, and fans welcomed him back to the painting world. Despite the fact that the Kowalskis got everything, they were the only ones who could have kept Ross’s name from disappearing.

As for all of Ross’s paintings the Kowalskis seized, they ended up in an unprotected warehouse until the Smithsonian took a collection of them.

Reference: Wealth Advisor (June 28, 2021) “Here’s Who Inherited Bob Ross’ Estate, And Where They Are Now”

Suggested Key Terms: Estate Planning Lawyer, Wills, Inheritance, Asset Protection, Executor

How Do You Keep Inheritance Money Separate?

Families with concerns about the durability of a child’s marriage are right to be concerned about protecting their children’s assets. For one family, where a mother wishes to give away all of her assets in the next year or two to her children and grandchildren, giving money directly to a son with an unstable marriage can be solved with the use of estate planning strategies, according to the article “Husband should keep inheritance in separate account” from The Reporter.

Everything a spouse earns while married is considered community property in most states. However, a gift or inheritance is usually considered separate property. If the gift or inheritance is not kept totally separate, that protection can be easily lost.

An inheritance or gift should not only be kept in a separate account from the spouse, but it should be kept at an entirely different financial institution. Since accounts within financial institutions are usually accessed online, it would be very easy for a spouse to gain access to an account, since they have likely already arranged for access to all accounts.

No other assets should be placed into this separate account, or the separation of the account will be lost and some or all of the inheritance or gift will be considered belonging to both spouses.

The legal burden of proof will be on the son in this case, if funds are commingled. He will have to prove what portion of the account should be his and his alone.

Here is another issue: if the son does not believe that his spouse is a problem and that there is no reason to keep the inheritance or gift separate, or if he is being pressured by the spouse to put the money into a joint account, he may need some help from a family member.

This “help” comes in the form of the mother putting his gift in an irrevocable trust.

If the mother decides to give away more than $15,000 to any one person in any one calendar year, she needs to file a gift tax return with her income tax returns the following year. However, her unified credit protects the first $11.7 million of her assets from any gift and estate taxes, so she does not have to pay any gift tax.

The mother should consider whether she expects to apply for Medicaid. If she is giving her money away before a serious illness occurs because she is concerned about needing to spend down her life savings for long term care, she should work with an elder law attorney. Giving money away in a lump sum would make her ineligible for Medicaid for at least five years in most states.

The best solution is for the mother to meet with an estate planning attorney who can work with her to determine the best way to protect her gift to her son and protect her assets if she expects to need long term care.

People often attempt to find simple workarounds to complex estate planning issues, and these DIY solutions usually backfire. It is smarter to speak with an experienced elder law attorney, who can help the mother and protect the son from making an expensive and stressful mistake.

Reference: The Reporter (Dec. 20, 2020) “Husband should keep inheritance in separate account”

Suggested Key Terms: Inheritance, Irrevocable Trust, Estate Planning Attorney, Community Property, Medicaid, Unified Credit, Gift Tax Return, Assets, Comingled Funds

What are Most Costly Mistakes with Social Security?

Motley Fool’s recent article entitled “5 Social Security Oversights That Could Cost You Thousands” says that these five Social Security mistakes could cost you thousands in your retirement.

  1. Claiming Social Security early while you’re still working. You can claim your Social Security retirement benefit as young as age 62, but your benefits will be permanently reduced when compared with the amount you would receive if you waited until your full retirement age. Social Security will also penalize you for continuing to work while collecting benefits, if you are younger than your full retirement age.
  2. Failing to claim Social Security by your 70th birthday. Once you hit age 62, your benefit increases the longer you wait to claim, until you reach 70. You don’t have to claim your benefit by your 70th birthday, but there is no more benefit for waiting at that point.
  3. Delaying past your full retirement age to claim Social Security spousal benefits. If you’re claiming Social Security benefits based on your own income record, it’s smart to wait past your full retirement age to start taking benefits. However, if you’re claiming based on your spouse’s benefits, there’s no benefit to delay beyond your full retirement age to claim. As a result, married couples of similar ages who have vastly different earned incomes have a dilemma: for you to claim spousal benefits, your spouse also has to have begun claiming benefits based on his or her own earnings record. This combination makes it less worthwhile for the primary breadwinner spouse to wait to collect benefits, if the spouse is expecting to take spousal benefits.
  4. Taxes on Social Security benefits are not adjusted for inflation. Originally, Social Security benefits weren’t taxed. However, in 1984, the government started taxing Social Security benefits once a person’s combined income reached $25,000. Even now, the income level where Social Security starts to get taxed is still at $25,000. Because there is no adjustment for inflation, this makes more of people’s Social Security income taxable. This easily costs even moderate-income retirees thousands of dollars of spendable income over the course of their retirements.
  5. “Tax free” income counts toward making Social Security taxable. Even traditionally tax-free sources of income, like the interest from in-state municipal bonds, is included in the calculations to see how much of your Social Security will be considered taxable. Therefore, seniors who own tax free municipal bonds as part of their retirement portfolio may be surprised to find that those bonds are what’s causing their Social Security to be taxed. Seniors who find themselves in that situation may want to reevaluate their choice to be invested in those tax-free municipal bonds.

Despite how simple Social Security may appear, these five situations show how mistakes can cost thousands of dollars.

Reference: Motley Fool (March 14, 2021) “5 Social Security Oversights That Could Cost You Thousands”

Suggested Key Terms: Elder Law Attorney, Social Security, Retirement Planning, Tax Planning, Financial Planning

Search
eNewsletter

Recent Posts
Categories